Few experiences produce greater dread than opening your mailbox to find an official letter from the Internal Revenue Service. If you just received an irs audit letter, your immediate instinct might be panic, confusion, or the urge to set the envelope aside. Taking a breath and understanding the notice is your first critical step. An audit notification does not mean you are going to jail, nor does it automatically mean you owe thousands of dollars. Millions of IRS notices are resolved each year with minimal adjustments or even additional refunds for the taxpayer.
However, ignoring the correspondence is the single costliest mistake you can make. The IRS operates under strict statutory timelines, and missing your response window forfeits essential appeal rights and triggers automated collections. By learning how to identify the specific type of audit notice you received, gathering the exact documentation required, and understanding your rights to representation, you can take control of the examination with professional poise.
Understanding Your Notice: Audit vs. Proposed Adjustment
The term “audit” is used broadly by the public, but the IRS categorizes compliance inquiries into distinct procedural tracks. Checking the notice number in the upper right-hand corner of your letter reveals the exact nature of the inquiry.
1. CP2000: Notice of Proposed Adjustment (The Automated Match)
A CP2000 is not technically a formal audit. It is an automated letter generated by the IRS Automated Underreporter (AUR) computer system. When a bank, brokerage, or client reports income on Form 1099 or Form W-2 that does not match Line 1 or Line 2 of your Form 1040, the system flags the difference. Under IRS Topic No. 654 on CP2000 Notices, this letter proposes adjustments to your tax liability. It provides a response form allowing you to agree, partially agree, or dispute the changes with supporting documentation.
2. Letter 566: Correspondence Examination (Audit by Mail)
Letter 566 (including variants like 566-S and 566-B) marks the formal beginning of a correspondence audit. Conducted entirely by mail, this represents approximately 75% to 80% of all IRS audits. The letter informs you that specific items on your tax return are under examination. Common targets include Schedule C business expenses, mileage write-offs, charitable donation receipts, or earned income tax credit qualifications. The letter lists the exact records you must furnish within 30 days.
3. Letter 2205: Office or Field Audit (In-Person Examination)
Letter 2205-A (for individuals) or Letter 2205-B (for businesses) signals an in-person examination. An office audit takes place at a local IRS field office, where you or your representative meet with an IRS Tax Compliance Officer. A field audit involves an IRS Revenue Agent visiting your place of business, your accountant’s office, or your home. Field audits are reserved for complex corporate entities, high-net-worth individuals, or substantial cash-intensive operations.
4. Letter 525: The 30-Day Examination Report
If an audit concludes with proposed adjustments that you have not agreed to, the IRS issues Letter 525 (commonly called the 30-day letter). It includes Form 4549 (Income Tax Examination Changes), outlining the additional taxes, interest, and penalties proposed. You have exactly 30 days from the letter’s date to agree or submit a formal written protest to the IRS Independent Office of Appeals.
5. Letter 531 / Notice CP3219A: The Statutory Notice of Deficiency (90-Day Letter)
If you fail to respond to Letter 525 or cannot reach an agreement, the IRS issues a formal Notice of Deficiency. Under federal law, this triggers an unbendable 90-day statutory clock. Your only remaining option to challenge the tax without paying first is filing a formal petition with the United States Tax Court.
| Notice / Letter Number | Inquiry Classification | Format | Standard Response Window |
|---|---|---|---|
| Notice CP2000 | Proposed Income Mismatch | Mail / Automated AUR | 30 Days (60 days if abroad) |
| Letter 566 | Correspondence Audit | Mail Inquiry | 30 Days |
| Letter 2205-A / 2205-B | Office or Field Audit | In-Person Interview | Call within 10 to 14 days |
| Letter 525 | 30-Day Preliminary Report | Appeal Rights Notice | 30 Days strict |
| Letter 531 / CP3219A | Statutory Notice of Deficiency | Legal Assessment Notice | 90 Days (Tax Court deadline) |
The Strict 30-Day Rule and How to Request an Extension
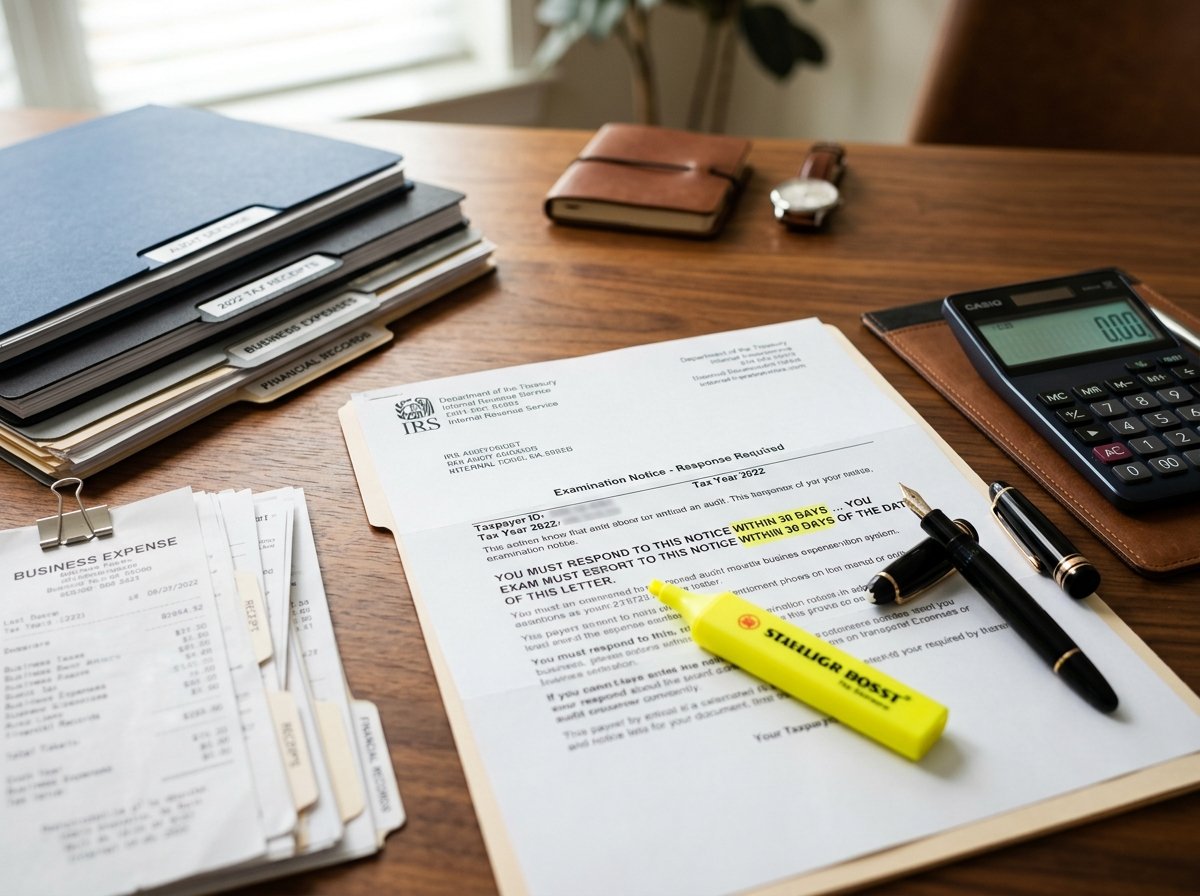
Almost every initial audit letter provides a 30-day deadline from the date of the letter (not the date it arrived in your mailbox). If you need additional time to retrieve bank archives, locate old receipts, or retain a CPA, do not wait until day 29 to act.
The IRS routinely grants a one-time 30-day extension upon request, provided you contact them before the original deadline expires. You can request this extension by calling the direct phone number listed in the top right corner of the notice, or by sending a written extension request via fax or certified mail. When speaking with the IRS representative, note their name, employee identification number (badge number), and the agreed-upon new deadline.
Whenever mailing correspondence to the IRS, always utilize United States Postal Service (USPS) Certified Mail with Return Receipt Requested. Under Internal Revenue Code Section 7502 (the “timely mailed, timely filed” rule), the postmark on a certified mail receipt serves as legal proof that you responded within the statutory window, protecting you against lost mail claims.
To understand the statute of limitations governing how many prior years the IRS can review, examine our detailed analysis on how far back the IRS can audit your tax returns.
Document Gathering and the Burden of Proof
Under IRS Publication 556 (Examination of Returns, Appeal Rights, and Claims for Refund), the legal burden of proof rests entirely on the taxpayer. When you claim a deduction, credit, or expense on your return, you must possess contemporaneous documentation substantiating the claim.
Strategic Rules for Preparing Audit Documentation
- Provide Only What Is Requested: Answer the specific questions on the Information Document Request (IDR). Never volunteer records, receipts, or explanations for tax years or items not under examination.
- Organize With Numbered Exhibits: Present receipts and invoices in clear chronological order corresponding directly to lines on your tax return. Create an index sheet mapping each receipt to its matching bank statement debit.
- Never Send Original Records: Always send photocopies or digital PDF files. Keep the original paper documents in your personal records. Government files can be misplaced during routing.
- Redact Unrelated Sensitive Data: Redact irrelevant personal details (such as medical diagnosis codes or minor children’s Social Security numbers on routine invoices) unless specifically relevant to the deduction.
Failing to substantiate deductions can lead to accuracy-related penalties under Internal Revenue Code Section 6662, which adds a mandatory 20% penalty to any unpaid balance. Learn how penalty assessments compound by reviewing our breakdown of IRS penalties, interest calculations, and relief options.
Your Rights as a Taxpayer: Form 2848 and Professional Representation
You do not have to face an IRS auditor alone. Under the Taxpayer Bill of Rights codified under Internal Revenue Code Section 7803(a)(3), you have the statutory right to quality service, the right to challenge the IRS position, the right to appeal, and the right to retain professional representation.
The Power of Form 2848 (Power of Attorney)
By executing IRS Form 2848 (Power of Attorney and Declaration of Representative), you authorize a licensed professional to manage the audit on your behalf. Under Treasury Department Circular 230, three classes of professionals hold unlimited representation rights before the IRS:
- Certified Public Accountants (CPAs): Specialists in forensic record reconstruction, accounting reconciliation, and tax code interpretations.
- Enrolled Agents (EAs): Federally licensed tax practitioners authorized directly by the U.S. Department of the Treasury.
- Tax Attorneys: Legal advocates specializing in tax litigation, formal administrative appeals, and criminal tax defense.
Once your representative files Form 2848 with the IRS Centralized Authorization File (CAF) unit, the IRS must direct all future telephone calls, written inquiries, and examination meetings to your representative. In an office or field audit, you are not required to appear in person unless the IRS issues an administrative summons. Having an experienced advocate prevents inadvertent admissions and keeps the scope of the inquiry focused solely on the items listed in the initial notice.
To determine whether your audit warrants an accountant or legal counsel, consult our comparative guide on hiring an IRS audit lawyer versus an enrolled agent or CPA, or explore our full suite of IRS audit representation and defense strategies.
What Happens After the Examination: The Three Audit Outcomes
When the examiner completes their review of your submitted documentation, the case concludes with one of three formal outcomes:
1. No-Change Audit (The Best Outcome)
The auditor accepts your documentation, verifies your deductions, and finds your tax return completely accurate as filed. The IRS issues a formal “no-change” letter, closing the examination without any additional tax, penalty, or interest assessments.
2. Agreed Changes
The auditor proposes adjustments (such as disallowing a portion of home office deductions or reclassifying an expense), and you agree that the adjustment is legally accurate. You sign Form 4549 (Income Tax Examination Changes), waiving further appeal rights, and pay the agreed amount or establish an installment agreement.
3. Unagreed Changes (Appeals Protocol)
If you disagree with the auditor’s conclusions, do not sign Form 4549. Signing forfeits your right to appeal. Instead, request an unagreed report (Letter 525). Within 30 days of receiving this notice, your representative can file a formal written protest with the IRS Independent Office of Appeals. Appeals officers are tasked with settling disputes impartially based on the “hazards of litigation,” meaning they frequently negotiate substantial reductions to avoid taking cases to court.
Action Steps to Take Right Now
If you are holding an open IRS letter, follow this disciplined four-step protocol immediately:
- Locate the Date and Form Number: Confirm whether you are dealing with a CP2000, Letter 566, or Letter 2205, and calculate your exact 30-day response deadline.
- Review the Questioned Items: Pull your filed Form 1040 for the tax year in question and compare the figures against the IRS explanation sheet.
- Gather Contemporaneous Records: Collect receipts, bank statements, canceled checks, and mileage logs supporting the challenged entries. Do not alter or backdate any documentation.
- Consult a Licensed Tax Representative: Schedule a consultation with a CPA or tax controversy advisor before submitting documents or contacting the auditor. Having professional oversight early saves thousands in potential assessments.
Frequently Asked Questions
Is an IRS CP2000 notice considered an official audit?
Technically, no. A CP2000 notice is an automated proposed adjustment generated by the IRS Automated Underreporter (AUR) computer system when third-party reporting (like 1099s or W-2s) does not match your filed return. However, it functions similarly in practice because failing to respond will cause the IRS to assess the proposed taxes, interest, and penalties automatically.
How long do I have to respond to an IRS audit letter?
Most IRS audit letters and examination notices carry a strict 30-day response deadline from the date printed on the letter. You can typically request a 30-day extension by calling the examiner or sending a written request before the initial deadline expires.
What happens if I ignore an IRS audit letter?
Ignoring an IRS audit letter results in the IRS disallowing all questioned deductions or assessing proposed income. The agency will issue a formal Notice of Deficiency (90-day letter), and if still unaddressed, will commence automated collections including bank levies, wage garnishments, and federal tax liens.
Can an IRS correspondence audit expand into a full field audit?
Yes. If your correspondence response reveals substantial unsubstantiated deductions, unfiled tax returns, or badges of civil fraud, the examiner can transfer your case to a local field office Revenue Agent for an in-person, multi-year examination.
Do I have the right to hire a professional to handle the audit for me?
Yes. Under the Taxpayer Bill of Rights and Treasury Department Circular 230, you have the statutory right to be represented by a licensed CPA, Enrolled Agent, or Tax Attorney. By filing Form 2848 (Power of Attorney), your representative communicates with the IRS directly on your behalf, so you do not have to speak with the auditor.
How should I mail my response documents to the IRS?
Always send response packages via USPS Certified Mail with Return Receipt Requested, or an IRS-approved private delivery service (like FedEx or UPS) with tracking. This provides legal proof of timely filing under Internal Revenue Code Section 7502.